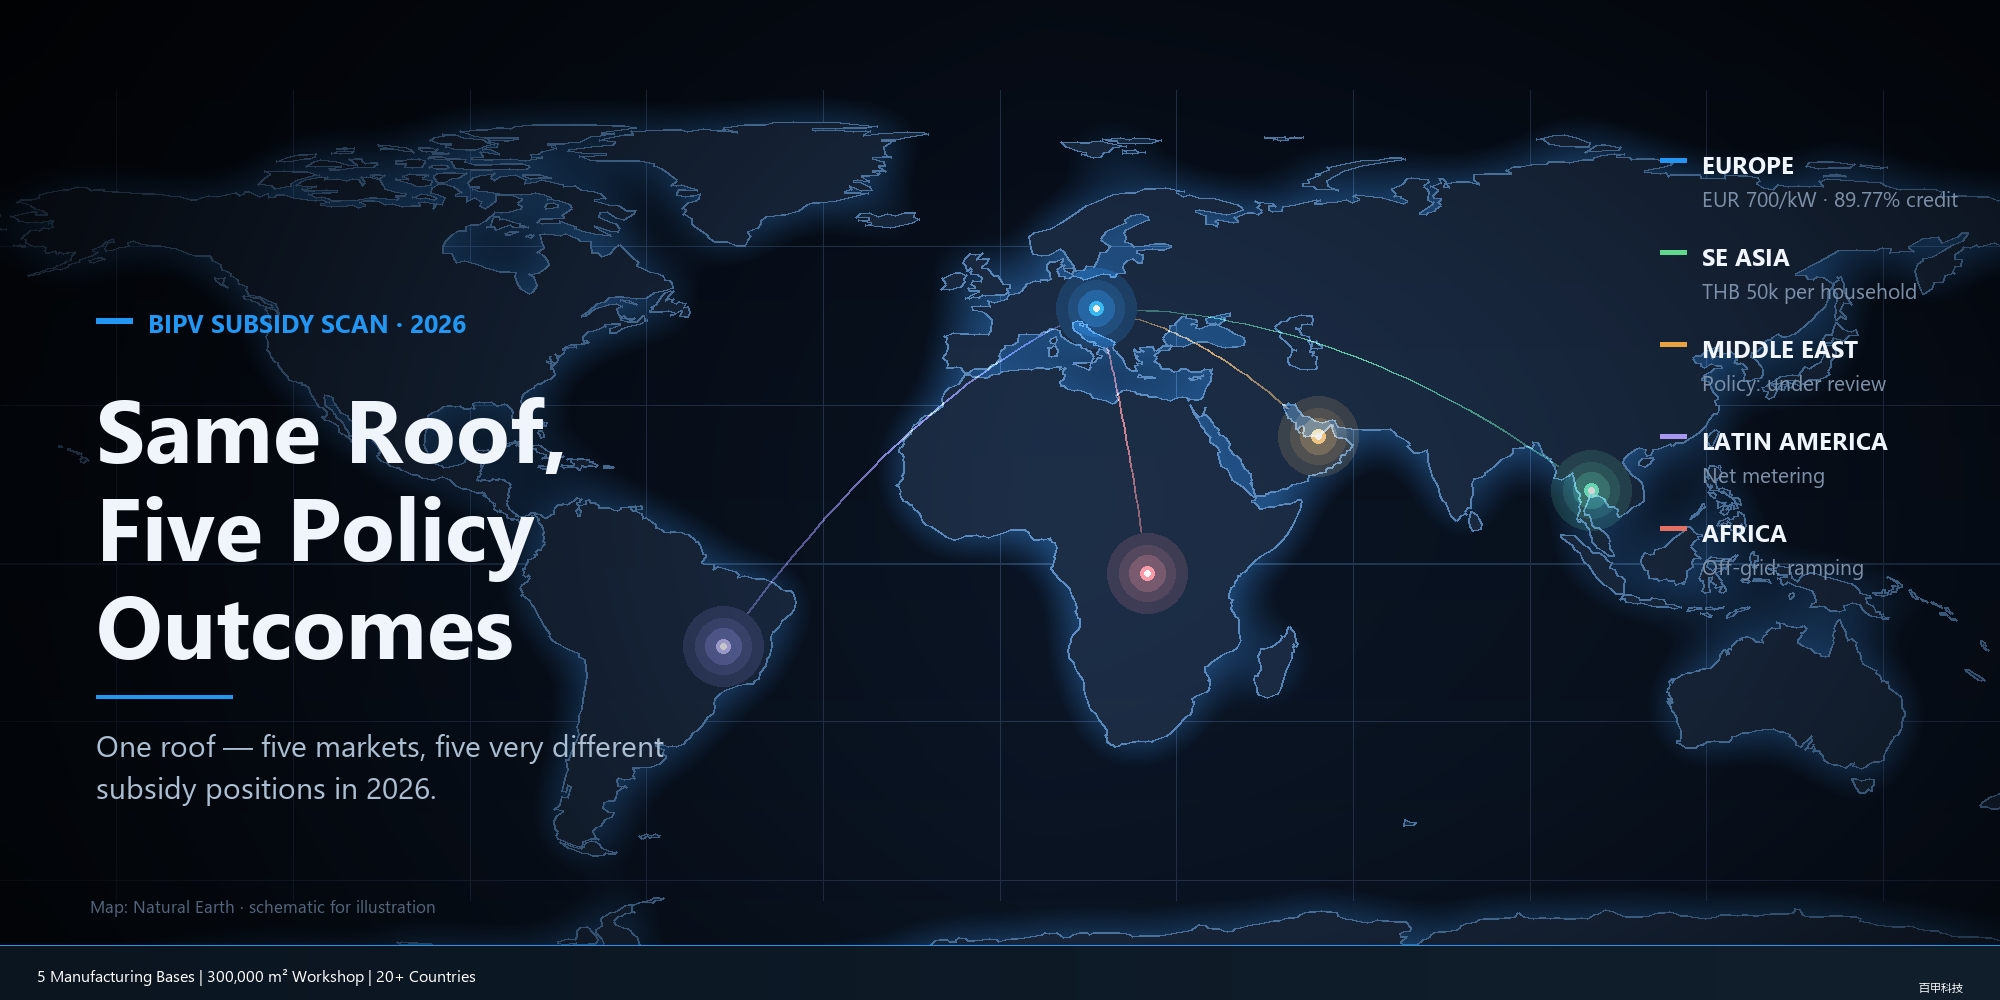
The same rooftop can receive completely different incentives in Vienna, Bangkok, or Dubai.
In 2026, BIPV incentives across five major overseas markets are diverging rapidly. Some markets are expanding dedicated BIPV programs, some are shifting support from installed capacity toward building integration, and others are scaling incentives back. Project owners need to assess whether their market is still within an incentive window and whether their project qualifies for a dedicated BIPV scheme or only general distributed-solar support.
This article provides a policy snapshot of five markets, three key questions, three industry trends, a decision framework, and FAQs.
Policy Snapshot: Five Major Markets in 2026
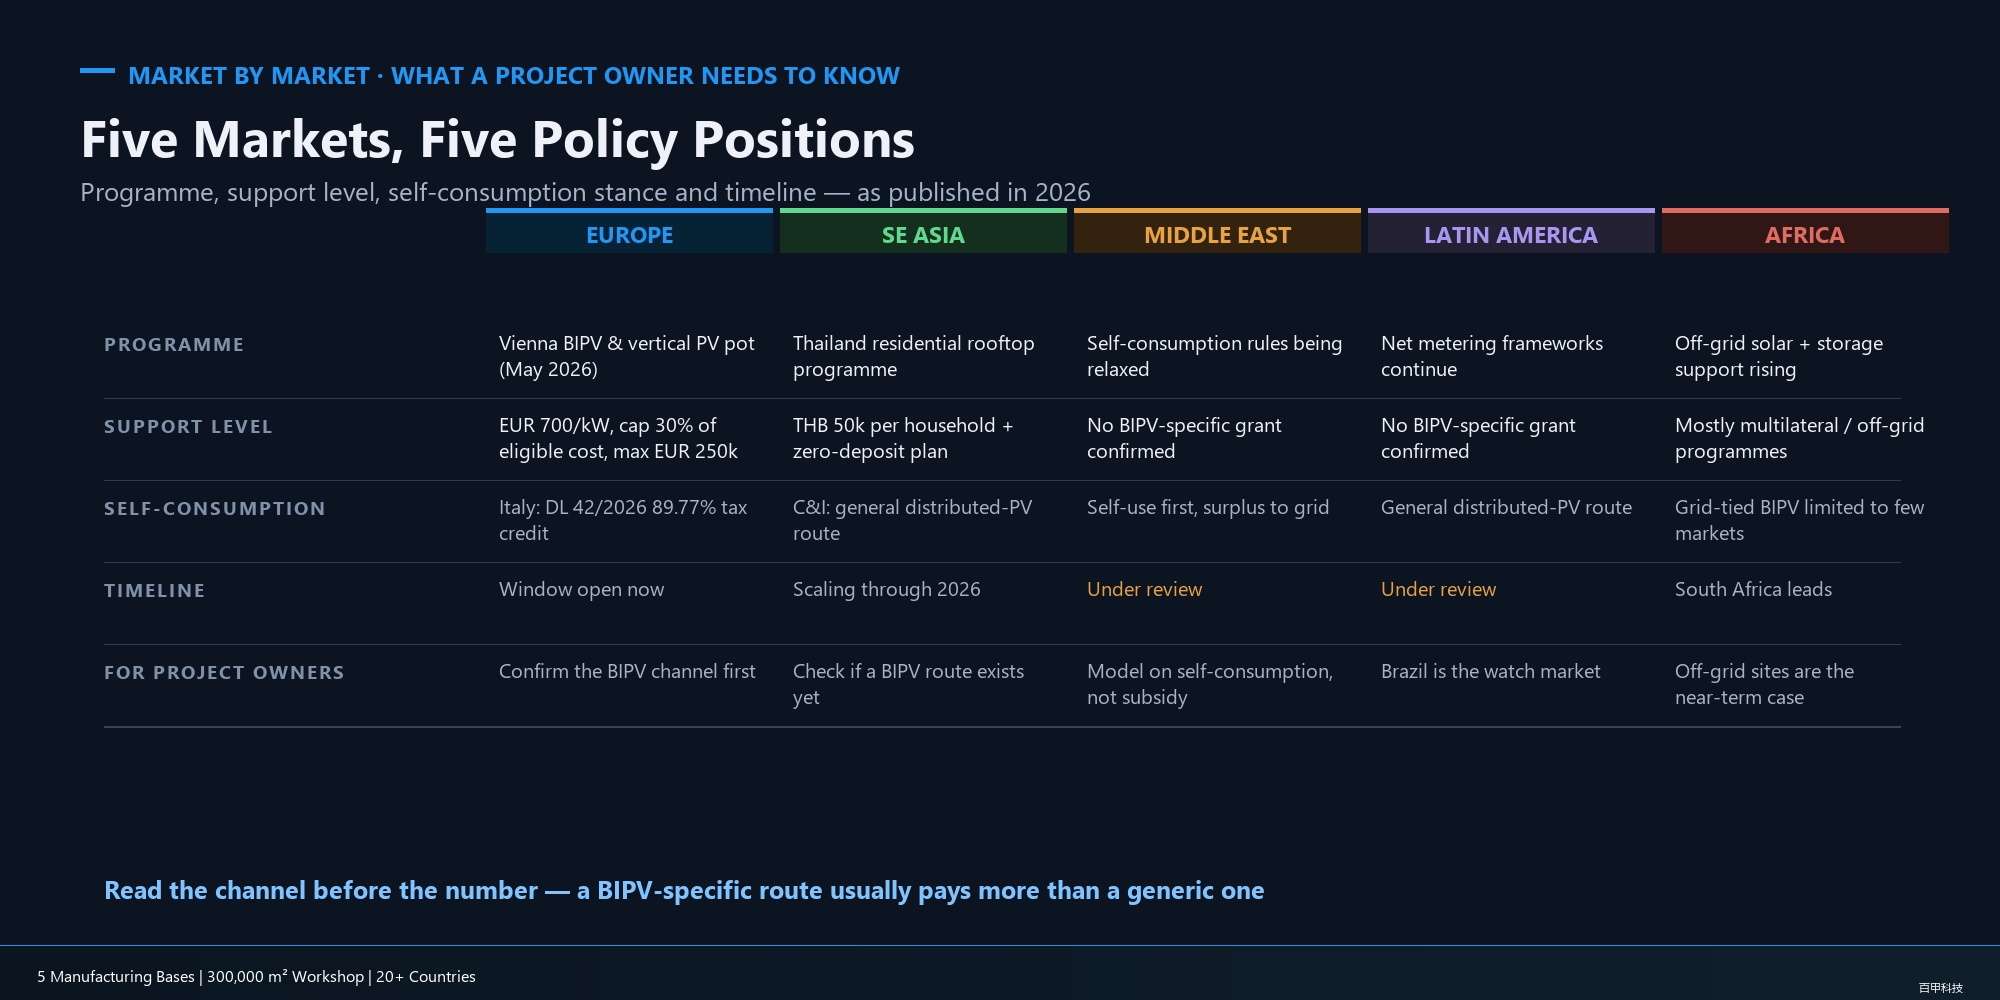
Europe: Combined Grants and Tax Credits
Europe has some of the most active BIPV incentive policies in 2026. Several countries and cities have launched dedicated programs that may coexist with tax credits and feed-in tariffs, subject to local rules.
Vienna, Austria: A €7 million program for BIPV and vertical photovoltaics launched in May 2026. Building-façade BIPV systems of 3 kW–1,000 kW may receive €700/kW, capped at 30% of eligible costs and €250,000 per system. Vienna targets 800 MW of solar capacity by 2030; installed capacity reportedly reached 330 MW in February 2026.
Italy: BIPV projects in 2026 may be eligible for multiple incentive measures:
| Policy |
Eligible applicants |
Incentive |
| Home Bonus 50% |
Owner-occupied primary residence |
50% tax credit, capped at €96,000 |
| Home Bonus 36% |
Second residential property |
36% tax credit, capped at €96,000 |
| Reduced VAT 10% |
Households and businesses |
VAT reduced to 10% (standard rate: 22%) |
| DL 42/2026 tax credit |
Businesses |
89.77% tax credit against tax payable on eligible investment |
| Transition 5.0 / Super-depreciation |
Businesses |
Investment of €2.5m–€10m; enhanced depreciation of 50%–180% |
| PNRR REC |
Businesses (shared with renewable energy communities) |
Direct grant up to 40% |
| GSE tariff |
Businesses (shared with renewable energy communities) |
Up to €120/MWh for 20 years |
The source estimates that combined incentives in Italy may cover 70%–80% of BIPV investment, making it one of Europe’s more generous markets for BIPV support.
Greece: The 2026 “Photovoltaics on the Roof” program is administered through HEDNO, the Greek distribution network operator, with a total budget of €238 million. Support is up to €16,000 for households and €10,000 for farmers. Solar incentives range from 45%–75% based on income, while battery storage incentives range from 90%–100%. The program requires battery installation to help manage high solar penetration on the grid.
Southeast Asia: Clearer Residential Support; C&I Projects Use General Schemes
Thailand is advancing a THB 50 billion residential rooftop solar program in 2026, offering THB 50,000 per household and zero-down-payment options. Under the proposed model, the power utility funds installation and sells electricity to homeowners at a discounted rate of no more than THB 3/kWh. The target is 5 GW of residential rooftop solar by the end of 2026, covering one million households.
Residential incentives are clearly expanding. Commercial and industrial BIPV projects may use general distributed-solar grid-connection routes, while dedicated BIPV support is still developing.
Vietnam, the Philippines, Malaysia, Indonesia, and other markets are continuing to refine distributed-solar grid-connection policies. Some allow surplus electricity to be exported to the grid. Dedicated BIPV incentives remain limited, so commercial and industrial projects may need to rely on general distributed-solar policies.
Middle East: More Flexible Self-Consumption, Limited Dedicated BIPV Support
Saudi Arabia, the UAE, and other markets have broadened the scope for commercial rooftop solar self-consumption. Some projects may consume generated power and export surplus electricity. Dedicated BIPV incentives remain underdeveloped, so commercial and industrial projects generally focus on self-consumption, with surplus exports as a supplement.
Under Saudi Vision 2030, renewable-energy targets continue to rise, but detailed BIPV incentive rules are still awaited.
Latin America: Stable Distributed Solar, Limited BIPV-Specific Support
Brazil: Renewal of PROINFA, the government renewable-energy incentive program, is under discussion, while general net-metering policies for distributed solar remain in place. Dedicated BIPV incentives are underdeveloped, so commercial and industrial projects may use general distributed-solar frameworks.
Mexico: Net-metering policies for distributed solar remain in place, giving commercial and industrial projects a relatively clear route to implementation.
Chile, Argentina, and other markets focus mainly on large ground-mounted power plants, and BIPV projects remain limited.
Africa: More Off-Grid Incentives, Limited Grid-Connected BIPV Policy
South Africa is one of the few markets with clearer policy routes for grid-connected BIPV; commercial and industrial projects may also use general distributed-solar grid-connection frameworks.
Kenya, Nigeria, Tanzania, and other markets are seeing more support for off-grid solar and storage, often through projects backed by multilateral institutions, the World Bank, or the African Development Bank. Grid-connected BIPV policy is still developing in most African markets.
For off-grid BIPV projects at mines, camps, and industrial parks, owners may need to review incentive programs for off-grid solar.
Three Key Questions
Is Your Market Expanding Incentives or Scaling Them Back?
Several European markets, including Vienna, Italy, and Greece, are supporting BIPV, while some Southeast Asian markets are expanding residential incentives. Incentive windows often last only 2–3 years, and missed opportunities may not return.
Can the Project Use a Dedicated BIPV Scheme or Only General Distributed-Solar Support?
Dedicated BIPV incentives may be higher than general incentives. For example, Vienna’s €700/kW support is specifically for BIPV and vertical photovoltaics, while conventional rooftop solar follows a different standard. Confirm eligibility before calculating project economics.
Can the Project Combine Multiple Incentives?
The source lists DL 42/2026, Home Bonus, Transition 5.0, PNRR REC, and GSE tariffs as potentially relevant to Italian BIPV projects. It estimates combined support could cover 70%–80% of investment. Eligibility and stacking restrictions must be checked for each project and under current local regulations.
Three Industry Trends
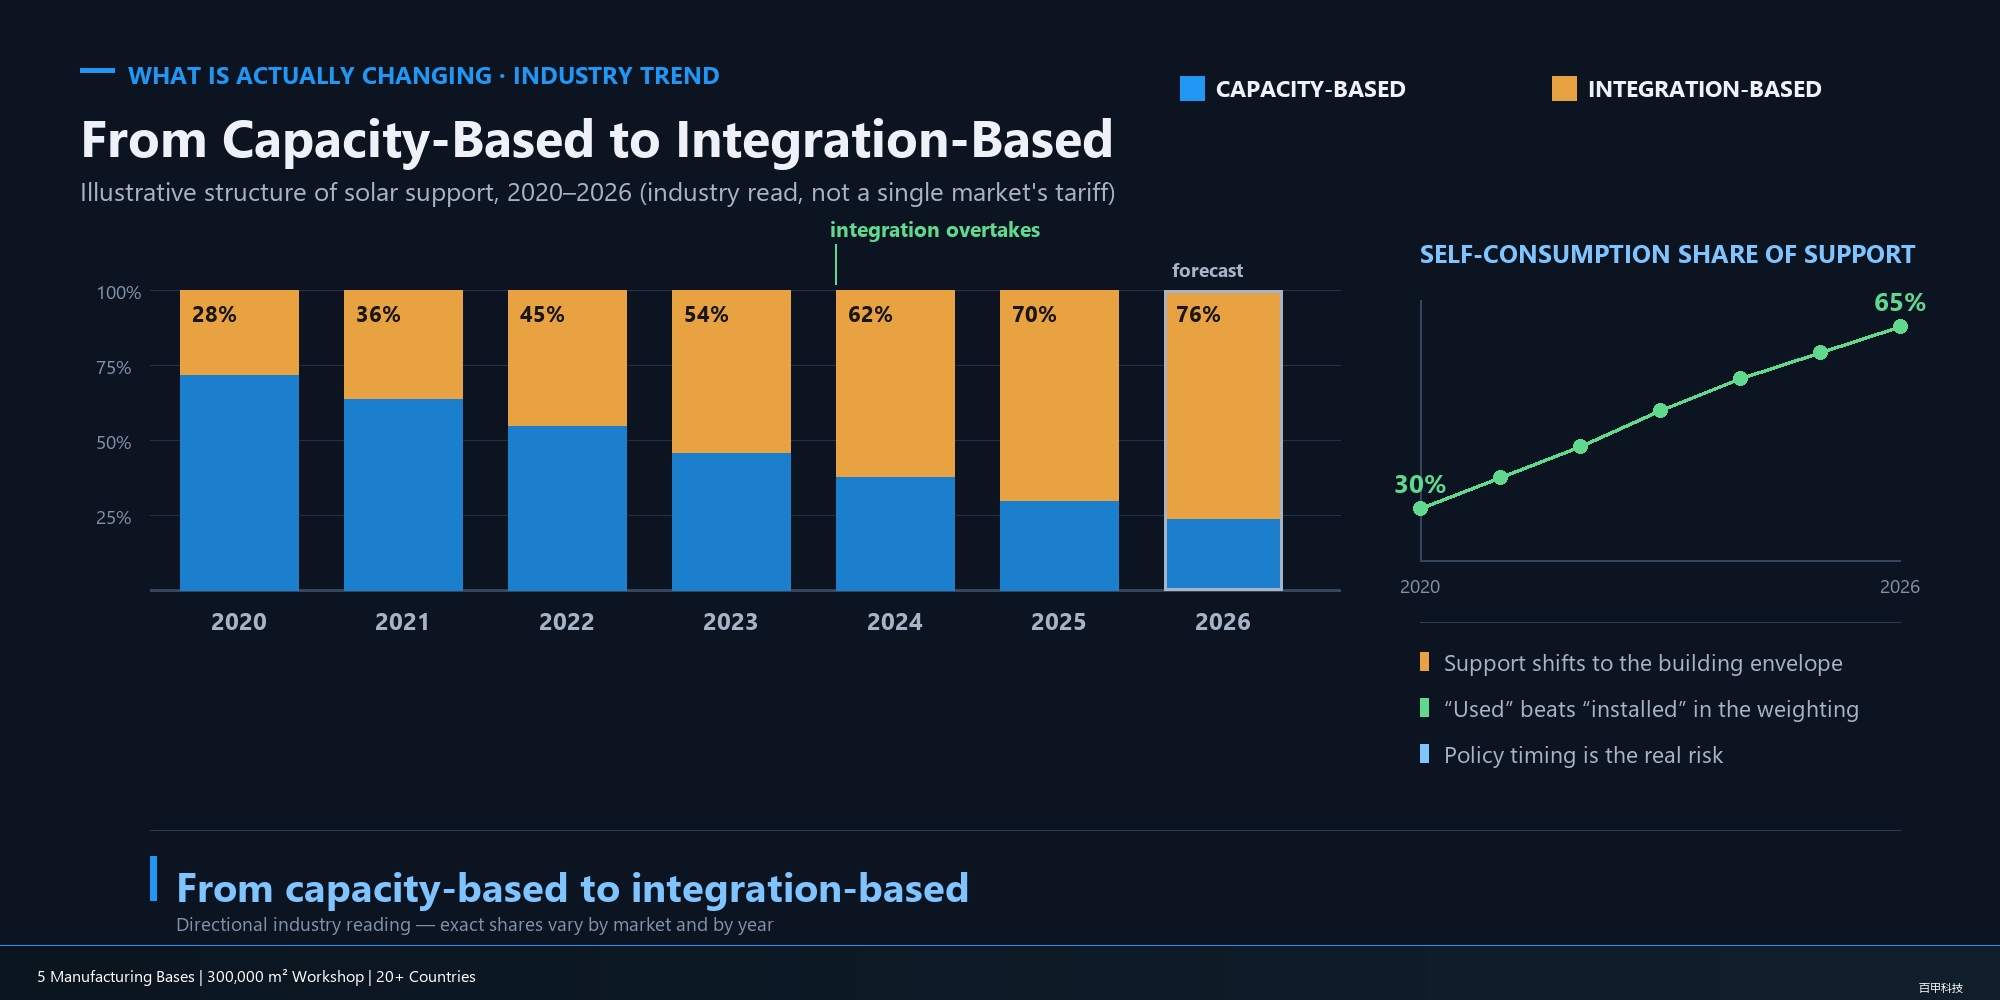
Incentives Are Shifting from Installed Capacity to Building Integration
Some European markets provide separate BIPV incentives because integrated systems can make better use of urban space. Integrated wall, façade, and roof systems may be treated differently from conventional modules mounted above a roof.
Self-Consumption Is Becoming More Important
Some markets are moving from “install and receive support” to incentives linked to electricity use. Support for exporting all generated electricity may decline, while self-consumed power may receive more favorable treatment.
Policy Timing Is a Key Risk
Policies announced in 2026 may change within months. Project owners should verify that incentives are still valid before contract negotiations, rather than checking only at signing.
A Simple Decision Framework
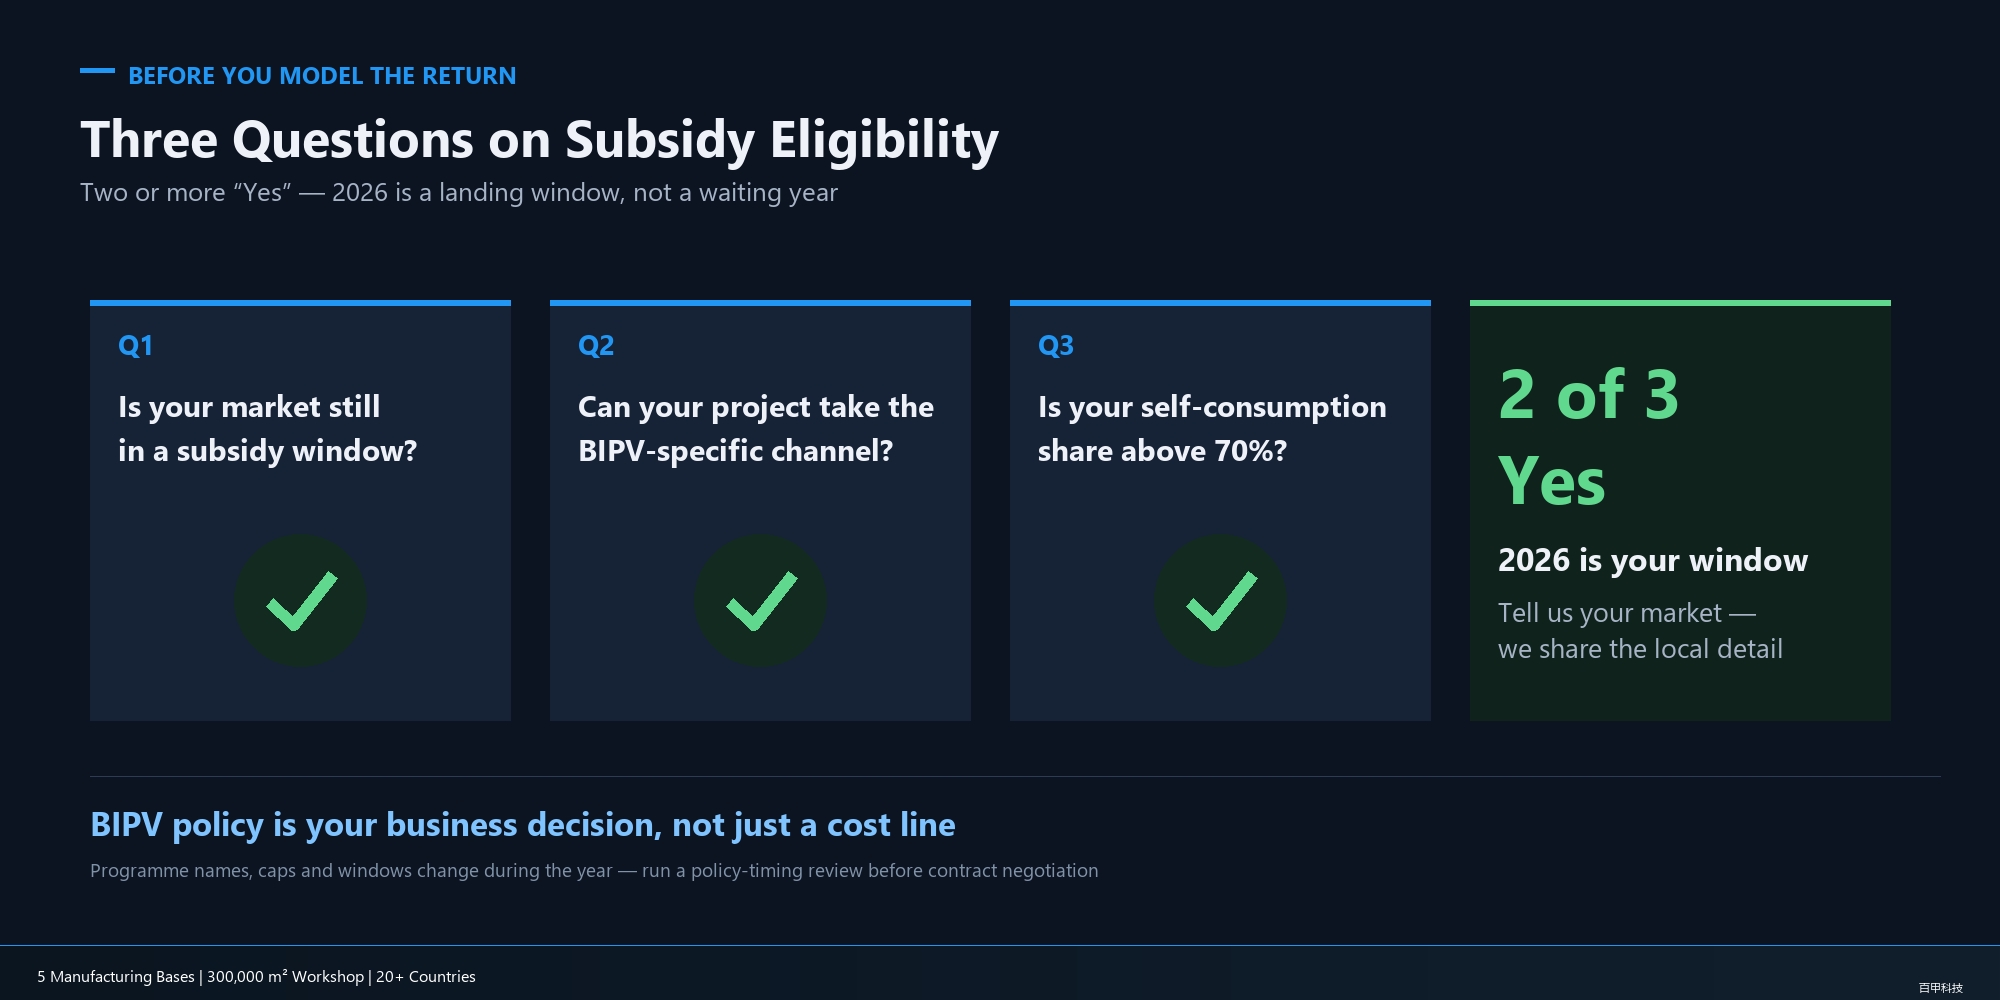
At the project-planning stage, overseas project owners should ask:
- Will there be a BIPV or distributed-solar incentive window in my market during 2026?
- Can my project qualify for a building-integration program, or only a general scheme?
- Can the self-consumption ratio exceed 70%?
If the answer to two of these three questions is “yes,” 2026 may offer a favorable window for project development.
FAQ
Q1: How much support can a BIPV project receive in Vienna?
Building-façade BIPV systems of 3 kW–1,000 kW may receive €700/kW, capped at 30% of eligible costs and €250,000 per system. A 100 kW system could therefore qualify for up to €70,000, subject to eligibility.
Q2: How does Italy’s 89.77% tax credit work?
According to the source, DL 42/2026 allows eligible businesses to offset tax payable with 89.77% of their BIPV investment. Note:
- The communication requirements under Article 38 of DL 19/2024 must be met.
- A confirmation from GSE is required that the investment meets the technical requirements of the MIMIT decree dated 24 July 2024.
- Whether this can be combined with measures such as Transition 5.0 depends on the specific case and applicable rules.
Q3: Can commercial and industrial projects receive Thailand’s THB 50,000 subsidy?
The THB 50,000-per-household subsidy is primarily aimed at residential rooftops. Commercial and industrial projects may use general distributed-solar grid-connection routes; dedicated BIPV support is still developing.
Q4: When will the Middle East introduce dedicated BIPV incentives?
The timing is unclear. Saudi Arabia and the UAE are mainly easing self-consumption rules, while detailed BIPV incentives are still awaited. Check the latest publications from the relevant local authorities before planning a project.
Q5: Which Latin American market is worth watching?
Brazil. Discussions on PROINFA renewal continue, net-metering policies for distributed solar remain in place, and commercial and industrial BIPV projects have a relatively clear implementation route.
Q6: What are the main BIPV use cases in Africa?
Off-grid settings such as mines, camps, and industrial parks are the main opportunities. The policy framework for BIPV is still developing in Africa.
Q7: Can BIPV incentives be combined with general distributed-solar incentives?
Often not for the same investment, because anti-cumulation rules may apply. Different types of support—such as tax credits and feed-in tariffs—may sometimes be combined. Check the relevant local rules.
Practical Recommendations for Project Owners
1、Verify policy validity before project approval—do not apply 2025 rules to a 2026 project without checking.
2、Prioritize dedicated BIPV incentive routes where eligible; they may offer better support than general schemes.
3、Consider self-consumption scenarios, as incentives may increasingly favor on-site use over full export to the grid.
4、Assess whether incentives can be combined; the source estimates that combined measures in markets such as Italy may cover 70%–80% of investment.
5、Some European and Southeast Asian markets may offer favorable opportunities in 2026, but incentive windows can be short and are subject to change.
Which market are you operating in? Contact us and we’ll share BIPV incentive information relevant to your region.
Email: info@xzbesta.com